Most people think of life insurance as something that only helps their family after they pass away. That is the main purpose of life insurance: to provide money to the people you choose as beneficiaries when you die.
But many modern life insurance policies can also include living benefits.
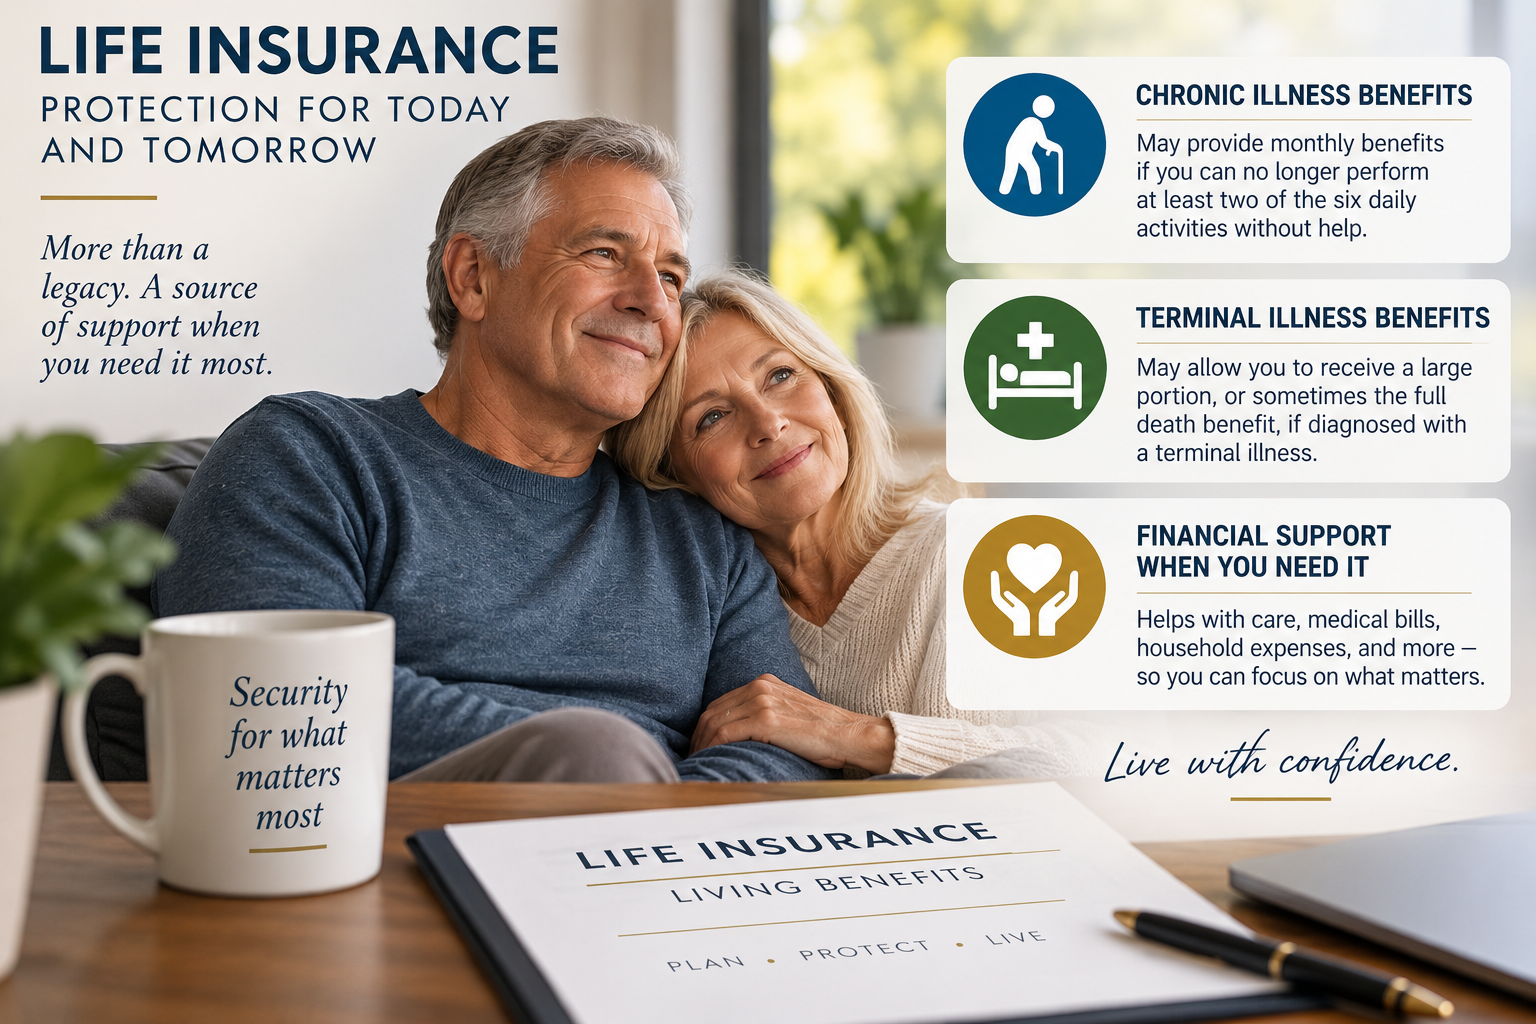
Living benefits allow the policyowner to access part of the life insurance death benefit while they are still alive if certain serious health conditions occur. These benefits can help if someone becomes chronically ill, can no longer perform basic daily activities without help, or is diagnosed with a terminal illness.
That means life insurance may do more than protect your family later. It may also help protect you while you are living.
What Are Living Benefits?
Living benefits are features or riders added to a life insurance policy that allow you to receive part of the death benefit early under certain circumstances.
The National Association of Insurance Commissioners describes an accelerated death benefit, also known as a living benefit, as a feature that lets you take money from your death benefit if you are diagnosed with a terminal illness and expect to die soon.
Some policies also include benefits for chronic illness or long-term care needs. The exact rules depend on the insurance company and the policy, so it is important to review the policy details before buying.
The main idea is simple: instead of waiting until death for the policy to pay, certain living benefit riders may allow the insured person to use some of the money sooner when they need it most.
Chronic Illness Benefits
A chronic illness benefit may allow you to access part of your life insurance death benefit if you become chronically ill and can no longer perform basic daily tasks without help.
The standard trigger is usually based on Activities of Daily Living, often called ADLs.
The IRS lists six common activities of daily living:
Eating
Toileting
Transferring
Bathing
Dressing
Continence
A person may be considered chronically ill if they are unable to perform at least two of these six activities without substantial assistance for at least 90 days because of a loss of functional capacity.
In plain English, this means the benefit may become available if someone can no longer do basic daily tasks by themselves, such as bathing, getting dressed, using the bathroom, eating, or moving from a bed to a chair without help.
This type of benefit can be extremely important because chronic illness can create major financial pressure. A person may need home care, family support, medical equipment, transportation, help with bills, or other assistance.
Monthly Benefits for Chronic Illness
Some life insurance policies with chronic illness or long-term care-style riders may pay benefits on a monthly basis when the insured person qualifies.
For example, if a person can no longer perform two of the six activities of daily living without help, the policy may allow them to receive a monthly benefit from the life insurance policy. That money can help pay for care, household expenses, or other needs.
This can be especially valuable because chronic illness is often not a one-time event. A person may need help month after month. Monthly benefits can help create a source of money during a difficult period, instead of forcing the family to rely only on savings.
The benefit amount, waiting period, maximum payout, and qualification rules depend on the policy. Some policies accelerate part of the death benefit. Others may have different rider structures. Either way, the purpose is to provide financial help while the insured person is still alive.
Terminal Illness Benefits
A terminal illness benefit works differently.
If the insured person is diagnosed with a terminal illness, the policy may allow them to request a large portion, or sometimes the full amount, of the death benefit while they are still alive.
The IRS defines a terminally ill person as someone certified by a physician as having an illness or physical condition that can reasonably be expected to result in death within 24 months from the date of certification.
This benefit can give the person access to money immediately, instead of requiring the family to wait until after death.
That money may be used for medical bills, household bills, family needs, final expenses, travel, caregiving, or simply to reduce financial stress during a very serious illness.
The Money Comes From the Death Benefit
It is important to understand that living benefits are usually an advance on the life insurance death benefit.
That means if you use part of the benefit while you are alive, the amount paid to your beneficiaries after death may be reduced. For example, if someone has a $250,000 life insurance policy and receives part of that amount early through a living benefit, the remaining death benefit may be lower.
This does not make the benefit bad. It simply means the policy is doing part of its job earlier.
Instead of only protecting loved ones after death, the policy may also help protect the insured person during a serious illness.
Why Living Benefits Matter
Living benefits matter because serious illness can create financial problems long before death occurs.
A person may be alive but unable to work. They may need help bathing, dressing, eating, or moving around the house. They may need a caregiver. A spouse or adult child may have to miss work to help. Bills may continue even while income drops.
That is why life insurance with living benefits can be valuable.
It can help provide money during the illness, not only after it is over.
For many families, that can make a major difference.
What to Ask Before Buying
Not every life insurance policy includes the same living benefits. Before buying a policy, ask:
Does the policy include living benefits?
Does it include chronic illness benefits?
Does it include terminal illness benefits?
Can benefits be paid monthly?
What triggers the benefit?
Is the standard based on two of six activities of daily living?
Is there a waiting period?
How much of the death benefit can be accessed early?
Will the remaining death benefit be reduced?
Are there fees or charges for using the rider?
These questions matter because the details can vary from one policy to another.
Bottom Line
Life insurance is not only about what happens after you die.
With living benefits, a life insurance policy may also help while you are still alive.
If you become chronically ill and can no longer perform basic daily tasks without help, some policies may allow you to receive monthly benefits. If you are diagnosed with a terminal illness, some policies may allow you to request part or even all of the death benefit immediately.
That money can help with care, bills, medical needs, household expenses, and other financial pressure during a serious illness.
The right life insurance policy can protect your family after death.
But with living benefits, it may also help protect you while you are living.