When people shop for health insurance, the monthly premium is usually the first number they look at.
That makes sense. The premium is the amount you pay every month to keep your health insurance active. It is the easiest number to compare, and it has an immediate effect on your budget.
But the lowest monthly premium is not always the best health plan.
A cheaper premium can look attractive, especially when money is tight. But health insurance is not only about what you pay each month. It is also about what you may have to pay when you actually use the plan.
That is where many people get surprised.
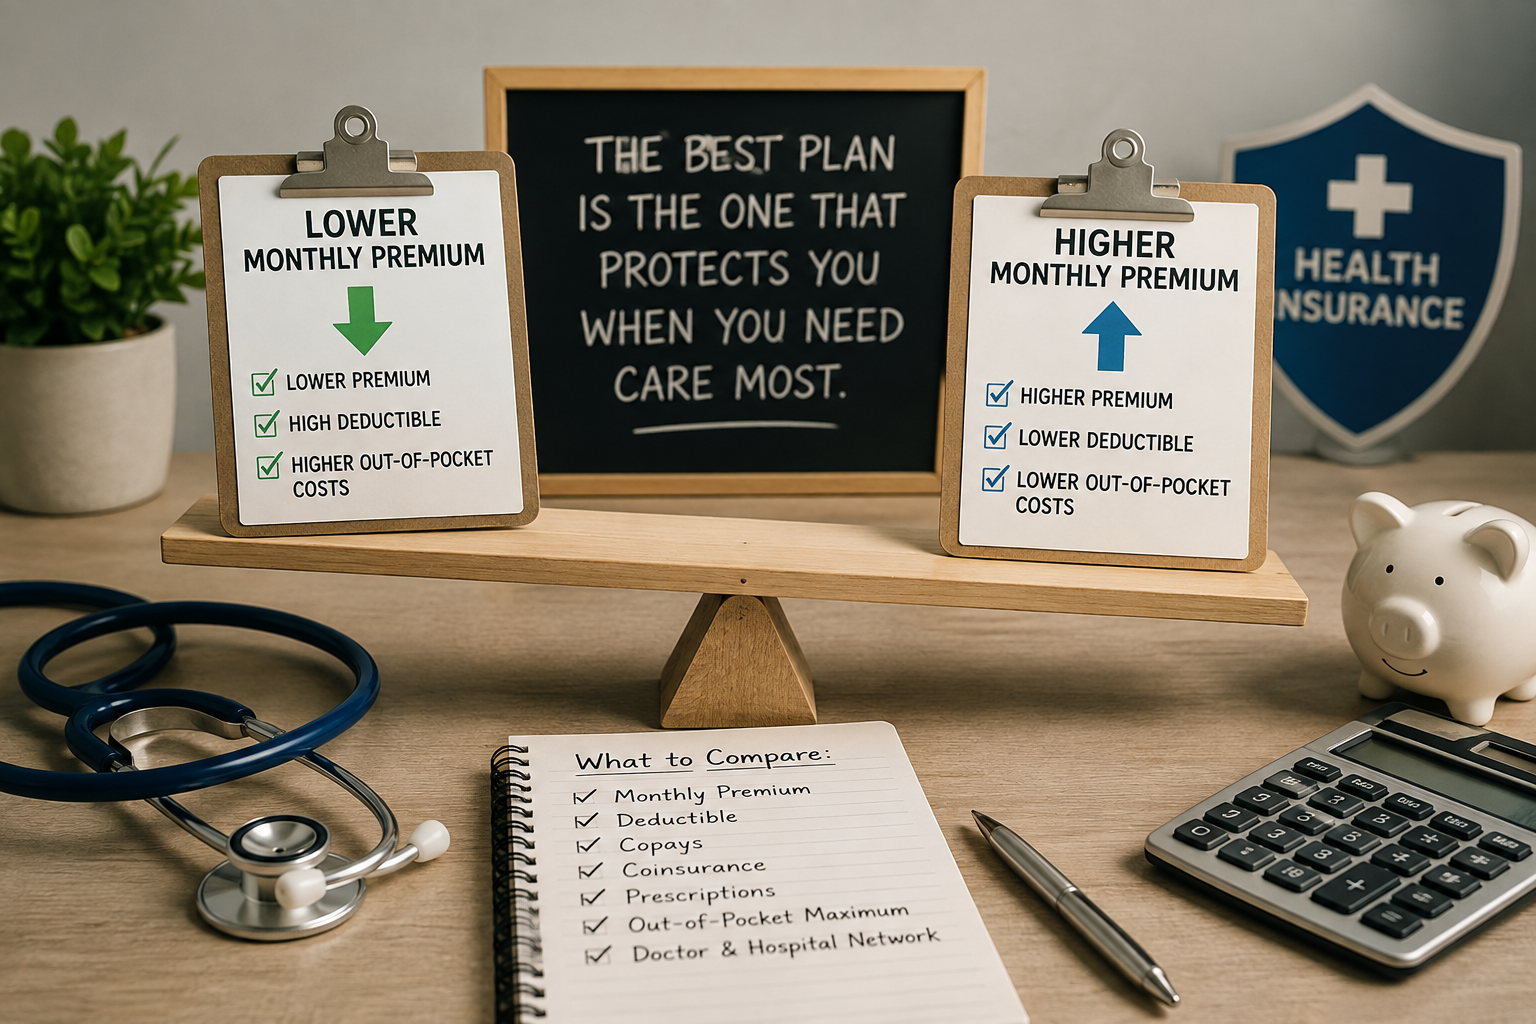
A plan may have a low monthly premium but a high deductible, higher copays, higher coinsurance, or a higher out-of-pocket maximum. That means the plan may be affordable every month but expensive when you need medical care.
HealthCare.gov advises consumers to compare estimated total yearly costs, not just the premium, when choosing a Marketplace plan. That includes the premium, deductible, copays, coinsurance, and out-of-pocket costs.
The Premium Is Only One Part of the Cost
The monthly premium is what you pay to keep the plan active.
But that does not mean the plan pays for everything once you have coverage.
Depending on the plan, you may still have to pay:
Deductibles
Doctor visit copays
Specialist copays
Prescription costs
Emergency room copays
Coinsurance
Hospital costs
Out-of-pocket expenses
This is why two plans can look very different once you actually need care.
One plan may cost more each month but have lower costs when you go to the doctor, fill prescriptions, have tests done, or end up in the hospital.
Another plan may cost less each month but leave you responsible for much more if something happens.
The right choice depends on the person. Someone who rarely uses medical care may care more about the monthly premium. Someone who takes medications, sees specialists, has children, expects surgery, or does not have emergency savings should look much closer at the total cost of the plan.
A Low Premium Can Mean Higher Costs Later
Many lower-premium health plans shift more of the cost to the member when care is used.
That does not make the plan bad. It just means the tradeoff needs to be understood.
For example, a person may choose a plan because it has a low monthly premium. But then they later discover that the plan has a high deductible, expensive specialist visits, high prescription costs, or a large out-of-pocket maximum.
If that person stays healthy all year, the lower premium may work out fine.
But if they have an emergency room visit, need imaging, have surgery, or spend even one night in the hospital, the savings from the lower monthly premium can disappear quickly.
This is especially important with ACA Marketplace plans because plan categories are based on how costs are split between the insurance company and the member. HealthCare.gov explains that Bronze, Silver, Gold, and Platinum categories are based on how you and the insurance plan share costs.
In simple terms, lower-premium plans often require the member to pay more when care is used. Higher-premium plans often provide more predictable costs when care is needed.
The Out-of-Pocket Maximum Matters
One of the most important numbers to review is the out-of-pocket maximum.
The out-of-pocket maximum is the most you should have to pay in a plan year for covered in-network services. Once you reach that amount, the plan pays 100% of covered in-network services for the rest of the year. HealthCare.gov describes this as the total amount you would have to pay no matter how much covered care you get during the plan year.
This number is often more important than people realize.
A plan may have a low premium and even a low deductible, but still have a high out-of-pocket maximum. That means if you have a serious medical issue, you could still be responsible for thousands of dollars.
For 2025 Marketplace plans, HealthCare.gov states that the out-of-pocket limit cannot be more than $9,200 for an individual and $18,400 for a family.
That does not mean every plan has an out-of-pocket maximum that high. Many plans are lower. But it does show why looking only at the monthly premium can be misleading.
A plan is not just what it costs when you are healthy.
It is also what it could cost when something goes wrong.
Bronze, Silver, and Gold Are Not About Quality
Many people misunderstand the metal levels.
Bronze, Silver, Gold, and Platinum do not mean one insurance company gives better doctors or better care than another. The metal level mainly describes how the cost is shared.
A Bronze plan usually has a lower monthly premium, but the member usually pays more when care is used.
A Silver plan is usually more balanced.
A Gold plan usually has a higher monthly premium, but lower costs when care is used.
That does not mean everyone should choose Gold. It also does not mean Bronze is always bad. It depends on the person’s budget, health needs, medications, doctors, and ability to handle unexpected bills.
The mistake is choosing only by premium and ignoring the rest of the plan.
A Simple Example
Imagine two plans.
Plan A costs less each month but has a high out-of-pocket maximum.
Plan B costs more each month but has lower costs when care is used.
If you never go to the doctor, Plan A may save money.
But if you have a hospital stay, surgery, expensive test, or ongoing medical issue, Plan B may end up being the better deal even though the monthly premium is higher.
This is why the cheapest plan is not automatically the best plan.
The better question is:
What is the total risk?
A person should ask:
What will this plan cost me each month?
What will it cost if I go to the doctor?
What will it cost if I see a specialist?
What will prescriptions cost?
What happens if I go to the emergency room?
What happens if I am hospitalized?
What is the most I could owe for covered in-network care this year?
Those questions give a much clearer picture than the premium alone.
Why This Matters Even More Now
Marketplace costs have become harder for many people to navigate.
KFF reported that the average ACA Marketplace deductible rose from $2,759 in 2025 to $3,786 in 2026, an increase of more than $1,000. KFF also reported that more enrollees shifted into higher-deductible plans after enhanced premium tax credits expired.
That makes it even more important for consumers to understand what they are buying.
When monthly premiums rise, many people naturally look for the cheapest option. That may be understandable, but it can also lead people into plans with higher deductibles and higher out-of-pocket exposure.
Saving money each month is helpful.
But saving $50 or $100 per month may not feel like a good tradeoff if the plan leaves you with thousands of dollars in bills after a major medical event.
The Best Plan Is the One That Fits Your Situation
There is no single best health plan for everyone.
The best plan for one person may be the wrong plan for someone else.
A healthy person who rarely uses medical care may choose differently than someone who takes several prescriptions. A family with children may choose differently than a single adult. Someone with savings may be comfortable taking on more out-of-pocket risk. Someone without savings may need a plan with more predictable costs.
That is why health insurance should be reviewed based on the full picture, not just the monthly price.
Before enrolling, it is important to compare:
Monthly premium
Deductible
Copays
Coinsurance
Prescription coverage
Doctor network
Hospital network
Out-of-pocket maximum
A good agent should explain all of these before a person enrolls. The goal is not just to find the lowest premium. The goal is to help the person understand what the plan may actually cost if they need to use it.
Bottom Line
The lowest monthly premium is not always the best health plan.
Sometimes it is the right choice. But sometimes it only looks good because the real costs are hidden in the deductible, copays, coinsurance, prescription costs, emergency room costs, hospital costs, or out-of-pocket maximum.
When choosing a health plan, do not ask only:
“What is the monthly premium?”
Ask:
“What could this plan cost me if I actually need medical care?”
That is the question that helps you choose a plan with your eyes open.
Health insurance should not just be affordable when you are healthy. It should also make sense when you need it most.